

Ally: Bank, Auto & Invest

- 15.91K Reviews
- 4.4
- Downloads
- 1,000,000+
Our take on Ally: Bank, Auto & Invest from Appgk
Ally: Bank, Auto & Invest is the kind of finance app that makes a strong first impression because it brings several money tasks into one place. I can use it to check banking activity, keep an eye on an auto-finance relationship, and review investing information without jumping between unrelated services. That combination is its main appeal, but it also raises an important question: does it remain useful after the first week, when the novelty of a single finance hub wears off?
My answer is mostly yes, especially for someone already comfortable with Ally Financial and looking for a regular money-management routine rather than a one-time budgeting tool. The app is free, aimed at everyone, and its broad scope makes it more practical than a simple account viewer. At the same time, its value depends on how much of the Ally ecosystem you actually use. If you only need a basic bank balance, a simpler banking app may feel less busy. If you want a single place to revisit several financial priorities, this app has a more convincing long-term case.
From quick first impression to a lasting money habit
Why the first week feels useful
During the first few days, the biggest benefit is orientation. Finance often becomes stressful when information is scattered across banking, vehicle payments, and investment accounts. A unified app reduces the number of places I need to remember, which makes it easier to form a simple routine: open the app, review what changed, and decide whether anything needs attention.
That routine matters more than flashy presentation. A finance app earns its place when it helps me notice an unusual transaction, remember an upcoming responsibility, or understand whether my available money matches my plans. Ally: Bank, Auto & Invest is designed around that wider view, so it feels more useful than an app limited to one narrow financial task.
Best Parts of Ally: Bank, Auto & Invest
Things to Keep in Mind About Ally: Bank, Auto & Invest
The app comes from Ally Financial, a developer with a clear connection to the services represented inside it. That gives the experience a more coherent feel than an independent aggregator trying to pull information from many unrelated institutions. The trade-off is equally clear: the app is most compelling when my financial life already fits the Ally setup.
I also like that the entry point is not limited to people who describe themselves as investors. The banking side can be the everyday anchor, while auto finance and investing become areas I check when necessary. This makes the app approachable for someone who wants to become more organized gradually instead of learning a complicated financial dashboard all at once.
News and Features Related to Ally: Bank, Auto & Invest

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A realistic everyday scenario
Imagine checking the app on a weekday morning before paying bills. I might first look at the bank balance, scan recent activity, and then move to the auto section to keep a vehicle-related obligation in view. If I am also investing through Ally, I can review that part without opening another service. The useful decision is not simply “look at everything”; it is deciding what deserves action today and what can wait.
That workflow is more valuable than repeatedly opening an app just to admire a combined dashboard. I would use the banking area frequently, the auto area around payment planning or account checks, and the investment area on a calmer schedule. Treating every section as something that needs daily attention would create unnecessary anxiety and encourage short-term reactions.
Don't want to read the full review?
One practical tip is to separate monitoring from decision-making. I can check balances and activity often, but I do not need to make an investment change every time the market moves or revisit an auto account without a reason. The app works best as a place for informed review, not as a prompt to constantly interfere with long-term plans.
What makes it different from the usual alternatives
Compared with a standard bank app, Ally: Bank, Auto & Invest has a wider financial role. A typical banking application may be better if all I need is spending visibility, transfers, and basic account management. Ally’s broader setup becomes an advantage when banking is only one part of the picture.
Screenshots
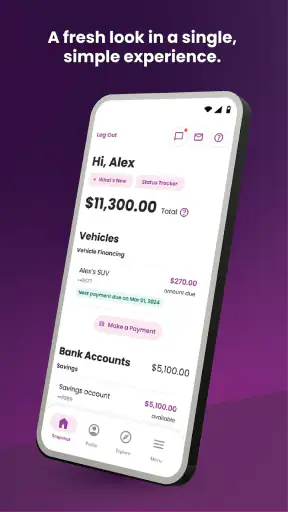
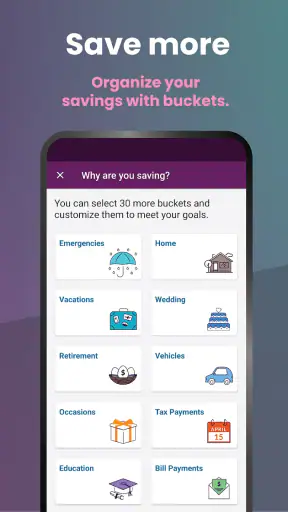
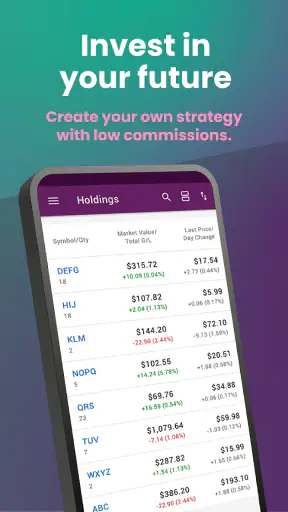
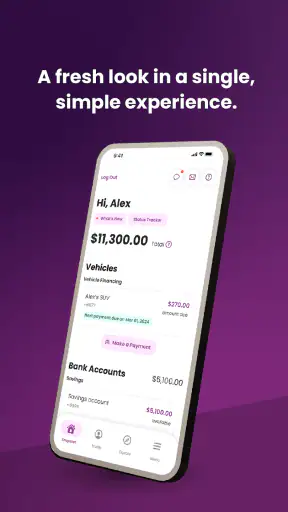
Compared with a dedicated investing app, this is less specialized in feel because investing sits alongside banking and auto finance. Someone who wants deep market research, highly focused trading tools, or a platform built entirely around portfolio analysis may prefer a specialist. The benefit here is continuity: I can connect investing with the rest of my financial life instead of treating it as an isolated hobby.
Budgeting apps also serve a different purpose. They can be better for categorizing spending across several institutions and building a detailed household plan. Ally’s strength is not necessarily replacing every budgeting method; it is reducing the friction of checking core Ally relationships. I would choose it for access and oversight, then use a separate budgeting system if I needed more elaborate planning.
Who will get the most from it
I think the app is a good match for Ally customers who want one recurring destination for banking, auto finance, and investing. It is also suitable for people who prefer a direct relationship with one financial provider rather than assembling several specialist apps. The broad design can help households that want a shared conversation about cash, vehicle obligations, and longer-term goals, even if each person uses the information differently.
It is less convincing for someone who does not use Ally services or who wants a neutral dashboard that combines accounts from many providers. It may also be the wrong choice for a person who wants a very detailed spending plan, extensive investment analysis, or a dedicated auto-payment tool with no other sections competing for attention. The free price removes a financial barrier, but it does not remove the need to choose the right kind of tool.
What remains valuable after the novelty fades
The month-to-month benefit is reduced friction
After the first week, the app’s value becomes quieter. I am not looking for a new discovery each time I open it. I want dependable access to the information that helps me make ordinary decisions: whether a payment has cleared, whether a balance looks right, and whether I need to follow up on something connected to my broader financial plan.
That kind of recurring value is easy to underestimate. A finance app does not need to entertain me if it consistently shortens the path between a question and an answer. When money is spread across separate services, even a small amount of extra navigation can make people postpone checking. Keeping related Ally activity together can make those checks feel more manageable.
The strongest long-term habit is a scheduled review rather than constant checking. I would set aside a regular moment to inspect recent activity, confirm important balances, and look at longer-term accounts with a calmer mindset. This approach helps prevent the app from becoming either ignored or compulsive. Its role is to support a routine, not become the routine’s entire focus.
Banking, auto finance, and investing need different rhythms
One subtle strength of the combined design is that it accommodates different review frequencies. Banking activity can deserve frequent attention because transactions and available money change often. Auto finance usually matters around payment planning and account status. Investing is generally better approached with patience and a longer view.
That difference also creates a potential weakness. Seeing all three areas together may tempt some users to apply the same urgency to everything. A daily bank check can be sensible for some people, but daily investment reactions are not automatically helpful. I would use the app’s unified access while keeping separate mental rules for each section.
A useful workflow is to begin with cash flow, move to obligations, and finish with long-term assets. That order keeps immediate needs in front of distant decisions. It also prevents an investment screen from distracting me from a banking issue that actually requires action. This is not a feature claim; it is the way I would get the most practical value from the app’s structure.
Where the app can support better financial conversations
Another lasting benefit is conversational. When financial information is divided among several apps, discussing money with a partner or family member can become a hunt for screenshots and separate logins. A consolidated view can make it easier to talk about what is happening now and what needs attention next.
That does not mean the app replaces a household budget or a financial professional. It simply gives the conversation a more concrete starting point. I can review the relevant account area, identify a question, and then decide whether the answer is straightforward or needs more research. The important habit is not sharing every detail casually; it is knowing where to begin.
The maintenance burden is fairly light, but not zero
The app is free, which makes keeping it installed easy, but financial tools still require maintenance from the user. I need to keep login access secure, pay attention to account notices, and avoid treating a clean interface as proof that every financial decision is simple. The app can organize information; it cannot decide what my priorities should be.
There is also a mental maintenance cost. A combined finance app can encourage me to add more checking than I need. If I open it whenever I feel uncertain, it may reinforce worry rather than improve control. I would rather establish a short review pattern and reserve extra checks for a specific reason, such as a transaction I do not recognize or a payment I expect to see.
Keeping the app useful also means knowing which section deserves attention. Someone who only uses banking may not benefit from repeatedly browsing investment or auto areas. The broader interface should be treated as an option, not a checklist. That is one of the clearest ways to prevent a multi-purpose finance app from becoming cluttered in daily use.
Sources of fatigue over time
The main source of fatigue is breadth. Combining several financial roles is convenient, but it can also make the app feel heavier than a focused banking tool. When I only want a quick balance check, extra financial categories may feel like visual noise, even if they are useful on another day.
Another possible frustration is the difference between visibility and action. Seeing a financial area in one app does not necessarily mean every task connected with it will feel equally simple. Banking, auto finance, and investing have different terminology and different consequences, so users may still need to slow down and read carefully rather than expect one uniform workflow.
I would also avoid judging the app by how often it can be opened. More frequent access is not the same as better money management. The app is at its best when it helps me complete a meaningful check or decision. It is less valuable when it becomes another source of notifications, uncertainty, or repeated balance watching.
What to expect from the current release
The current version is 26.14.0, and the app requires at least iOS 10. That makes device compatibility an important practical check before installing, especially if I am using older hardware or an older operating system. On a supported device, I would still allow time to become familiar with the way the three financial areas are organized rather than assuming the first screen tells the whole story.
The app has been available since April 26, 2012, which gives it a long presence in mobile finance. I see that longevity as a reason to evaluate it as a maintained financial utility rather than a novelty app. Still, long availability does not guarantee that its organization will suit everyone. My own test would be simple: after several weeks, can I reach the information I actually need without feeling pulled into sections I never use?
How public reception fits the practical picture
Ally: Bank, Auto & Invest holds a 4.4 average from roughly 41 thousand ratings, with more than 16 thousand written reviews. It has passed one million installs, so it clearly has a substantial audience rather than being a niche experiment. Those figures suggest that many people find the overall approach workable, but they do not remove the need to judge the app against my own financial setup.
Public approval is most meaningful here as a sign of familiarity and continued use, not as a promise that every workflow will feel perfect. Finance apps are unusually personal: one user may value a unified view, while another may consider the same breadth distracting. I would use the positive reception as encouragement to try it, then decide based on whether it supports a sustainable review habit.
My long-term verdict
After the initial appeal fades, I still see a solid reason to keep Ally: Bank, Auto & Invest installed when Ally banking, auto finance, or investing is part of my regular financial life. Its lasting strength is convenience with purpose: related money responsibilities can be checked from one place, while each area can follow its own review rhythm.
I would not recommend it as a universal replacement for every finance tool. A dedicated budgeting app may be better for detailed spending analysis, a specialist investment platform may suit advanced research, and a simpler bank app may be preferable for someone who wants only essential account access. The right choice depends on whether the wider Ally view reduces friction or adds unnecessary complexity.
For me, the app earns lasting space when I use it deliberately: check everyday banking, review auto obligations when relevant, and approach investing with patience. Its free access, Everyone age rating, broad financial purpose, and established presence make it easy to consider, while its multi-section design asks for a little discipline. The real test is not whether the app can show several parts of my financial life, but whether it helps me maintain a calmer, repeatable habit of paying attention.
Ally: Bank, Auto & Invest FAQ
What is Ally: Bank, Auto & Invest, and what can I do with it?
Ally: Bank, Auto & Invest is a mobile app that brings together Ally Bank, Ally Auto, and Ally Invest services in one place. After signing in, eligible customers can review account balances, transfer money, deposit checks, manage eligible auto-loan details, and monitor investments. The features you see depend on which Ally products you have and your account permissions, so it is not a complete replacement for every banking or investing service.
Is the Ally app safe to use for banking and investing?
The app includes standard security features designed to protect financial information, such as encrypted connections, secure sign-in, and account alerts or verification tools where available. However, no financial app is completely risk-free. Use the official app-store listing, keep your device and operating system updated, avoid public Wi-Fi for sensitive transactions, and never share passwords or verification codes. Investment accounts also carry market risk that security features cannot eliminate.
Can I deposit checks, transfer money, and pay bills through the app?
For eligible Ally Bank accounts, the app generally supports everyday tasks such as checking balances, moving money between accounts, sending transfers, depositing checks with your phone camera, and managing bill payments. Availability, limits, processing times, and eligibility can vary by account type and transaction. Before relying on a mobile deposit or transfer for an urgent payment, review the app’s confirmation details and applicable funds-availability rules.
Does the app let me manage Ally Auto loans and Ally Invest accounts?
Yes, the app may provide access to eligible Ally Auto and Ally Invest accounts alongside Ally Bank products. Auto customers can typically review loan information, payment details, and account activity, while investors may be able to view portfolios, research investments, and place trades depending on their account. The exact tools can differ by product, region, and account status, so some users may see only banking features after signing in.
Is Ally: Bank, Auto & Invest free to download, and are there any fees?
The application is generally free to download from the official Android or iOS store, but downloading the app does not mean every Ally service is free. Account fees, investment commissions or other charges, transfer rules, overdraft policies, and auto-loan terms depend on the specific product and current Ally disclosures. Check the pricing information for your account before opening a service or completing a transaction, especially when investing or transferring money.











